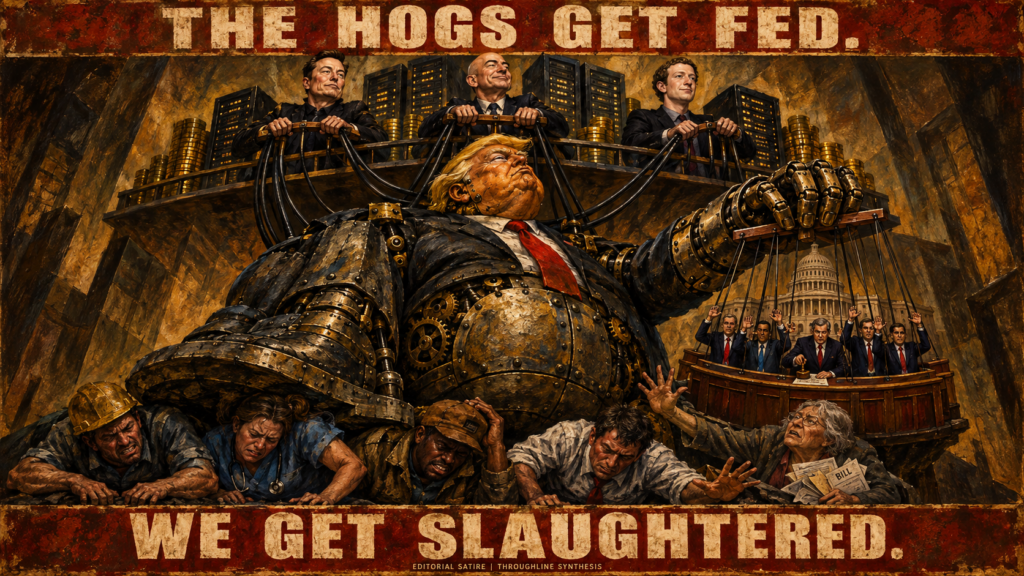
The 1% buy Congress. Trump and Congress serve up the laws and favors. The hogs get fed, and we get slaughtered.
How incredibly stupid can Americans be? This malignant lout is destroying them, and still they cheer. You would think the Republican rats would flee the Good Ship Sycophancy out of sheer self-preservation. But why assume preserving their party, much less their country, matters more than preserving their comfortable arrangements?
The deeper obscenity is not Trump alone. It is the proposition that people who own an extraordinary share of the country should also enjoy an extraordinary share of the power to govern it. We are supposed to call this freedom. Freedom for whom?
My objection is not that concentrated wealth might occasionally tempt somebody into misconduct. The concentration itself is objectionable. A democracy cannot promise political equality while treating the economic power to overwhelm that equality as sacred.
This November, the question is not whether Democrats have clean hands. It is whether Americans will remove the political protection surrounding Trump’s second-term excesses, then demand something better than the same comfortable arrangements under different management. An election that changes the officeholders without challenging their dependence on concentrated wealth is a change of personnel, not a democratic recovery.
Who owns the gains?
The Federal Reserve’s estimates for the second quarter of 2026 show the wealthiest 1% of households holding 50.9% of corporate equities and mutual-fund shares; the wealthiest 10% hold approximately 88.1%. [1] The bottom half hold 0.6%. [2] Half the households barely register.
Those figures describe a particular asset category, not every kind of wealth or every stock market on earth. [3] For total household net worth, the corresponding shares are 32.5% for the top 1%, approximately 68.9% for the top 10%, and 2.3% for the bottom half. [4] Correcting the denominator does not rescue the arrangement. It makes the accusation harder to evade.

A retirement account does not put a worker in the same position as somebody who can bankroll candidates, sustain litigation indefinitely, or finance institutions that decide which ideas deserve a hearing. Both may own assets. Only one can afford to turn ownership into a governing philosophy and employ other people to sell it.
Piketty: accumulated wealth becomes inherited power
Thomas Piketty’s contribution is not merely a collection of alarming percentages. His work examines how property, inheritance, taxation, and political institutions reproduce inequality, while insisting that those institutions can be changed. [5] The distribution of ownership is not a natural landscape we must admire from a distance. It is an arrangement society permits.
His formulation, r > g, means that returns on capital exceed economic growth; where fortunes are already unequal and enough returns are retained, that gap can amplify wealth concentration and make inherited advantages more persistent. [6] Piketty explicitly rejects treating this relationship as an automatic explanation of every change in inequality: saving, inheritance, taxes, institutional changes, and political shocks matter. [7]
Emmanuel Saez and Gabriel Zucman’s research in the Journal of Economic Perspectives estimates that average American national income per adult grew 1.4% annually from 1980 through 2018, while pretax income for the bottom half grew only 0.2% annually. [8] Their distributional accounts expose what aggregate growth conceals: the country can become richer without delivering comparable gains to most people.

Enormous rewards do not necessarily measure enormous contributions. Piketty, Saez, and Stefanie Stantcheva distinguish productive effort from bargaining for existing income; across 18 advanced economies, they found no systematic evidence that cutting top tax rates increased growth. [9]
Hudson: ownership can charge admission to life
Michael Hudson supplies the distinction that polite discussion so often avoids: producing wealth is not the same thing as extracting income from control over property, credit, or monopoly privileges. In his Review of Radical Political Economics article, he contrasts productive investment with a financial system organized around rent extraction, asset-price gains, indebtedness, and privatized infrastructure. [10]
Economic rent, in this argument, is income secured through ownership or privileged control beyond the costs of providing the underlying service, rather than a reward for creating an equivalent benefit. [11] The distinction is not between working and receiving a dividend. It is between financing useful activity and acquiring the power to charge everyone else for access.
Hudson describes a feedback loop in which lending against existing assets helps inflate their prices, larger prices support larger debts, and servicing those debts squeezes income available for consumption and production. [12] What looks like prosperity from the owner’s side can look like a rising admission charge from everybody else’s.
Consider the difference between building another home and bidding up the price of an existing home. Both may enrich an investor. Only one necessarily adds a place to live. Why should Americans be instructed to celebrate the investor’s gain without asking what the rest of the country received?
This is the rentier problem. The rentiers are not entitled to political immunity because their extraction arrives dressed as a contract, a fee, or a return on investment. Legality does not settle legitimacy.
Wolff: democracy stops at the workplace door
Richard Wolff takes the argument inside the enterprise. In Understanding Capitalism, he locates a central source of inequality in employers’ control over production’s surplus and argues that workplace hierarchy both produces and is reinforced by unequal wealth. [13]
Why celebrate democracy while exempting the institutions that organize our working lives? Wolff advocates democratic control of enterprises rather than leaving decisions about production and surplus to a small ownership class. [14]
Workers are told they are sovereign citizens, then told that decisions governing their economic security belong to somebody else. A formal right to object is not the practical means to resist.
That is why concentrated wealth is more than an offensive photograph of somebody’s yacht. It distributes the freedom to refuse. One person can wait out a dispute. Another cannot miss a paycheck.
The damage becomes political when institutions capable of balancing that power are weakened. Research by James Feigenbaum, Alexander Hertel-Fernandez, and Vanessa Williamson links right-to-work laws to reduced union political activity and estimates a 2-percentage-point decline in electoral turnout in affected counties. [15] These laws concern union financing, but their consequences reach beyond the workplace. [16] Telling people to vote while weakening the organizations that help them act together is not a serious commitment to democracy. It is an invitation to participate without the power to insist.

The conversion of money into government
Political scientists Jeffrey Winters and Benjamin Page explain why oligarchy need not abolish elections: great wealth can provide both the resources and the motivation to defend privileged material interests within a formally democratic system. [17] The wealthy do not need to agree about everything. They need sufficient influence over the decisions that protect their position.
Daron Acemoglu and James Robinson model how elites can offset losses of formal authority by investing in other means of influence. [18] Change the officeholders while leaving those resources untouched, and the owners can fight to reverse the change.
Martin Gilens and Page subsequently examined 1,779 policy cases from 1981 through 2002 and found substantial independent associations between policy outcomes and affluent preferences and business-group positions, but little or none for average citizens after those influences were accounted for. [19] This is observational research, not proof that voters never matter or that every policy was purchased.
Democratic erosion is measurable, too. V-Dem’s 2026 report puts America’s Liberal Democracy Index at 0.75 in 2024 and 0.57 in 2025. [20] That documents deterioration; it does not, by itself, identify how much concentrated wealth caused the decline.

A randomized experiment provides narrower but more direct evidence: identifying prospective visitors as campaign donors rather than local constituents made senior policymakers available between 3 and 4 times as often across 191 congressional offices. [21] Money was associated not merely with louder advertising but with privileged entry to the people making decisions.

Jeffrey Sachs calls this political dependence a central American failure, describing wealthy donors and organized lobbies obtaining favors from officials whose campaigns they finance. [22] His account connects private accumulation to public decisions about taxes, regulation, and expenditure. [23] This is not simply a problem of impolite billionaires. It is a system for converting wealth into durable advantage.

Look at the direction of Trump’s 2025 reconciliation law: the Congressional Budget Office projected average annual resource losses of approximately $1,200 for the lowest-income 10% and gains of approximately $13,600 for the highest-income 10%, over 2026 through 2034 in 2025 dollars. [24] Look who benefits.

You only need the deciding votes
You do not need to buy Congress wholesale. You need leverage where the decision is made. The House passed that law 218 to 214; 2 additional yes-to-no switches would have killed it. [25] The Senate divided 50 to 50 before the vice president intervened; 1 additional opposing senator would have defeated passage. [26] That is pivotal-vote arithmetic, not proof of purchased votes.

Different interests can cultivate different members on different issues. A handful of holdouts can become the center of attention while the broader machinery remains undisturbed. Do not confuse televised dissent with independence. The test is what survives into law.
Changing the party is not changing the structure
Many of my closest friends are lobbyists. Losing a majority need not destroy the commercial value of relationships with incumbents who survive. That is not a universal claim about fees, and professional fees are not campaign contributions. It is a warning against confusing a party’s defeat with the destruction of everybody’s comfortable arrangements.
Nor do Democrats get an exemption. Sachs explicitly includes wealthy donors to both parties in his critique of political dependence. [27] I call that a uniparty: not identical votes, but shared dependence on the class whose power should be challenged.
Piketty, Amory Gethin, and Clara Martínez-Toledano document another danger: across 21 Western democracies, left parties became increasingly associated with highly educated voters while high-income voters generally remained more associated with the right. [28] Their research does not establish that both sides are identical. It does challenge the comforting assumption that established left parties automatically remain effective political homes for working people.
I want Democrats to confront that problem, not congratulate themselves for possessing better manners. They could not recognize progress if you painted it on their foreheads when their first response is to ask whether the donors will tolerate it. A democracy reduced to this spectacle looks like rigor mortis, with careerists circling like flies on a dead dog’s eye.
Consider the nearly $25 million that United Democracy Project, the American Israel Public Affairs Committee’s super PAC, spent in the 2024 primary contests that defeated then-New York Democratic Rep. Jamaal Bowman and then-Missouri Democratic Rep. Cori Bush. [29] That outside group is not Democratic leadership, and money was not the only electoral factor. But the example shows why dissenting candidates face more than an argument over ideas. Wealth can intervene before the general election, helping determine which alternatives voters are allowed to consider viable. The question is not whether every challenger deserves victory. It is who can afford to define the contest.
The holdouts whose concessions protected wealth
The mechanism has names. In November 2017, Wisconsin Republican Sen. Ron Johnson threatened to oppose Trump’s tax bill unless it gave more favorable treatment to pass-through businesses, whose profits are taxed on their owners’ returns. After the provision was enlarged, he supported the bill. [30] This was not dissent against the upward redistribution. It was a demand to improve the terms for another group of owners.
Dick and Liz Uihlein and Diane Hendricks had contributed approximately $20 million to groups supporting Wisconsin Republican Sen. Johnson’s 2016 reelection. ProPublica’s examination of confidential tax records found that they subsequently claimed a combined $215 million in pass-through deductions in 2018. [31] Those were deductions from taxable income, not $215 million in tax savings, and not the incremental benefit of Wisconsin Republican Sen. Johnson’s amendment alone. The distinction matters because the actual arrangement is revealing enough.
There is a paper trail beyond matching donors to a vote. In December 2017 correspondence obtained from Treasury, Wisconsin Republican Sen. Johnson forwarded Wisconsin real-estate investors’ objections to senior tax writers and officials, and then-Texas Republican Rep. Kevin Brady, chairman of House Ways and Means, promised to keep improving the provisions. [32] Ordinary Americans are told to contact their representatives. These businessmen had their objections carried directly into the drafting process.
Wisconsin Republican Sen. Johnson denied that his position had anything to do with donors, saying he wanted pass-through businesses to remain competitive. He later acknowledged that his own company, Pacur, benefited: “Now, did my business benefit? Sure.” [33] The public-interest defense and the private benefit existed in the same sentence.
That arrangement did not expire with Trump’s first term. His 2025 law made the 20% qualified-business-income deduction permanent, and Wisconsin Republican Sen. Johnson voted for the legislation. [34] November’s question is not only who invented these privileges. It is who keeps renewing them.

Democrats supplied their own textbook example in 2022. Then-Arizona Democratic Sen. Kyrsten Sinema insisted on removing a proposed tightening of carried-interest taxation before supporting the Inflation Reduction Act. Carried interest is investment managers’ share of fund profits, which can receive favorable capital-gains treatment rather than ordinary-income treatment. [35] Americans who live on wages do not get to relabel their paycheck that way.
Since the beginning of the 2018 election cycle, then-Arizona Democratic Sen. Sinema had received at least $2 million in securities-and-investment-industry contributions, according to the Federal Election Commission data analyzed by OpenSecrets and reported by CNBC. The American Investment Council’s PAC contributed $10,000, while employees at KKR, Carlyle, and Apollo contributed more than $95,000 combined over the period identified in the report. [36] These are overlapping categories, not figures to add together.
The proposed carried-interest change was expected to raise approximately $14 billion over a decade. It disappeared, and then-Arizona Democratic Sen. Sinema voted yes in a Senate divided 50 to 50, with Vice President Kamala Harris breaking the tie. [37] Then-Arizona Democratic Sen. Sinema’s office said her decisions reflected Arizona’s interests, not donors’ wishes. [38] The relevant point is not that a prosecutor established a purchased vote. It is that an industry secured a valuable concession through a senator whose support the coalition could not spare.

When the officeholder also collects
Campaign money, personal income, and bribes are different things. Collapsing them into a single total would obscure how the system works. We should be able to condemn legally permitted conflicts without pretending they are criminal convictions, and to name proven bribery without hiding it behind the word “controversy.”
Then-West Virginia Democratic Sen. Joe Manchin’s disclosures, as examined by CNN, showed an Enersystems ownership interest worth between $1 million and $5 million and more than $536,000 in income from it in 2021. CNN also documented more than $400,000 in energy-interest campaign contributions during the third quarter of 2021. [39] The first stream went to the owner. The second supported the politician.
Then-West Virginia Democratic Sen. Manchin chaired the Senate’s energy committee while retaining that coal-business interest, and he ultimately helped negotiate and pass the 2022 climate legislation, which combined substantial clean-energy support with fossil-fuel concessions. [40] His office said he complied with Senate ethics and disclosure rules. [41] That defense raises the larger question: why do the rules permit such a substantial private interest to sit beside such consequential public authority?

Former Arizona independent Sen. Sinema’s subsequent career supplies another connection, though not proof of a deferred payoff. In March 2025, Hogan Lovells announced her arrival in its regulatory practice, along with her chief of staff as a policy adviser. [42] Publicly cultivated relationships can retain commercial value after voters are no longer part of the arrangement.
A separate February 2026 complaint by Campaign Legal Center alleged that former Arizona independent Sen. Sinema converted more than $700,000 in leftover campaign funds to personal use during 2025. It cited campaign reports covering travel, lodging, equipment, and staffing, among other expenses. [43] That is an allegation seeking an investigation, not an established finding of theft. The spending records are evidence to examine, not permission to declare the complaint proved.
For demonstrated criminal enrichment, look at former New Jersey Democratic Sen. Bob Menendez. A jury convicted him, and, in January 2025, he received an 11-year prison sentence for bribery, foreign-agent, and obstruction offenses. [44] Investigators found more than $480,000 in cash and gold bars worth more than $100,000 at his home, while the proven scheme involved official assistance to businessmen and Egypt. [45] His appeal remained unresolved in the reporting on September 24, 2026. [46]
For the military-contractor version, look at former California Republican Rep. Randy “Duke” Cunningham. He admitted receiving at least $2.4 million in bribes in return for using his office to influence appropriations and government contracts, and he failed to disclose the benefits on congressional financial reports and his tax return. [47] The benefits included an inflated home purchase, mortgage payments, yacht expenses, and furnishings. [48] This was not a metaphor about the military-industrial complex. It was a congressman monetizing his position inside it.
Trump pardoned former California Republican Rep. Cunningham in January 2021, after former California Republican Rep. Cunningham had served his prison sentence. [49] So much for the promised cleansing of Washington.

These cases substantiate real private benefits, serious conflicts, and proven corruption across party lines. They do not establish that every increase in every member’s wealth came from selling votes. The argument does not need that fantasy. It needs Americans to stop treating documented arrangements as acceptable merely because some of them remain legal.
The robes do not make the gifts disappear
Clarence Thomas was not merely accused of having rich friends. His own 2022 disclosure, filed in 2023, lists Crow-provided travel and acknowledges an earlier reportable real-estate transaction that he had omitted. [50] A judicial robe does not turn a billionaire’s hospitality into an institutional safeguard.
ProPublica documented a $6,200 tuition payment from Crow Holdings for Thomas’s grandnephew, whom Thomas was raising, and Thomas’s friend Mark Paoletta acknowledged that Crow paid for a year at each of 2 private schools. [51] Crow’s company also purchased properties from Thomas and his relatives for $133,363 in 2014. That was the total property-sale price, not a cash gift of that amount to Thomas alone. [52] Thomas said the transaction produced a capital loss and that the omission was inadvertent. [53]
Crow denied seeking to influence Thomas, while Thomas defended his earlier treatment of travel under the personal-hospitality exemption. [54] Those responses belong in the record. They do not answer why citizens should be comfortable with judges receiving extraordinary private benefits from wealthy political participants.
In January 2025, the Judicial Conference declined to act on a requested referral, citing amended disclosures, questions about its authority over Supreme Court justices, and other grounds. Its letter also described guidance limiting the clarified transportation-disclosure rule to 2022 and later years. [55] This was not a judicial finding that a particular decision had been purchased, nor a trial resolving every allegation.
The democratic injury extends beyond a provable transaction. Courts help determine the boundaries of public power. If extraordinary private benefits coexist with weak accountability at that level, the people asked to trust those boundaries have every right to be furious. We are not obliged to confuse the absence of a conviction with the presence of an acceptable system.

Trump’s second term is not an ordinary installment
Democratic misconduct is part of this story, not an alibi for the current administration. Bipartisan failure does not require us to pretend that every presidency operates at the same scale. Under Trump’s second presidency, the combination of family enrichment, presidential authority, and weakened oversight has become obscene.
Reuters’s review of Trump’s annual disclosure reported more than $1.4 billion in income from family crypto ventures during 2025, including almost $800 million connected to World Liberty Financial and $635 million from Trump meme-coin sales. The reporting described income received through his businesses and shared within the family, not $1.4 billion proved to be bribery or deposited exclusively into Trump’s personal checking account. [56] The president remained the beneficiary of the trust while his children managed the businesses. [57]
Meanwhile, his administration promoted crypto and reduced enforcement pressure on the industry. Ethics specialists interviewed by Reuters described the family’s enrichment from an industry the administration regulates as an unprecedented conflict of interest. [58] The White House denied conflicts and said the administration acted for the American people. [59] Americans are entitled to ask why serving them has become so extraordinarily remunerative for the governing family.
The scale is not the only outrage. At the beginning of his second term, Trump fired more than a dozen inspectors general overnight, removing officials whose job includes investigating waste and misconduct. [60] A presidency with enormous private interests is dangerous enough. A presidency that also weakens the people charged with examining government conduct is a different order of danger.
“The Democrats did it, too” is not a defense. It is an admission that Americans have tolerated far too much for far too long. Trump does not become less objectionable because the machinery predates him. The combination of private enrichment and weakened public scrutiny makes the need to confront that machinery more urgent, not less.

The institutions that sell war as common sense
Foreign policy does not float above these arrangements. It is made by officials, staffed through professional networks, debated by funded institutions, and financed with public money. The useful question is not whether everybody attended the same university. It is who supplied the money, who supplied the argument, who exercised authority, and who bore the consequences.
Yale is a real connection in some of these careers, not a substitute for tracing them. John Bolton’s official biography records both Yale degrees and his senior position at the American Enterprise Institute before government service. [61] A separate record documents the Project for the New American Century’s January 1998 appeal to President Clinton for regime change in Iraq, and ABC identified Bolton among signatories who later entered the Bush administration. [62] The meaningful connection is between organized advocacy and the subsequent exercise of state power.
That project crossed party boundaries in practice. Joe Biden and Hillary Clinton voted for the 2002 Iraq war authorization, which passed the Senate 77 to 23. [63] Obama’s administration later initiated the CIA program to arm and train anti-Assad rebels in Syria, which Trump ended in 2017. [64] These are distinct decisions, not proof that a single hidden committee directed every war.
For Ukraine, there is a measurable funding-and-amplification connection. A Quincy Institute study counted 1,247 think-tank mentions in selected New York Times, Washington Post, and Wall Street Journal coverage from March 2022 through January 2023. Of those mentions, 1,064 involved institutions receiving defense-sector support. [65] That is approximately 85%, not proof that 85% of the coverage was false.
The funding is not imaginary. The Atlantic Council’s own 2021 contributor list places both Lockheed Martin and Raytheon Technologies in the $100,000 to $249,999 category. [66] The concern is that institutions supported by military suppliers receive disproportionate opportunities to define the security debate. That can normalize military spending while leaving negotiation, restraint, and the public’s competing needs struggling for a hearing. The study does not establish that donors dictated particular articles, or that contractor interests explain Russia’s invasion.

The newer elite network is not identical to the old neoconservative network. JD Vance attended Yale Law School, and Peter Thiel supplied $15 million to the super PAC supporting his 2022 Senate candidacy. [67] The same reporting records Vance’s opposition to American involvement in the Ukraine war. [68] Treating every Yale graduate, billionaire patron, and foreign-policy hawk as interchangeable would conceal the actual relationships rather than expose them.
For Israel policy, the electoral machinery is concrete. By the end of September 2024, Miriam Adelson had contributed $100 million to the pro-Trump super PAC Preserve America. [69] The AIPAC-linked primary spending described earlier supplies another, distinct channel of political leverage.
By March 4, 2026, that debate concerned an actual U.S. military campaign against Iran, and the Senate rejected a motion to advance a war-powers resolution by 47 to 53. Pennsylvania Democratic Sen. John Fetterman joined Republicans against the motion, while Kentucky Republican Sen. Rand Paul joined the other side. [70] That procedural vote did not formally authorize the war, but it blocked an attempt to restrain it.
The donation record does not establish that Adelson purchased the Iran campaign, or that Pennsylvania Democratic Sen. Fetterman sold that vote. Trump also fired Bolton in 2019 after major disagreements, which is another reason not to portray the president as an inert object controlled by an undifferentiated network. [71] Influence must be investigated without erasing the responsibility of the people who actually make the decisions.
The indictment is institutional. Wealth can finance electoral survival and the production of respectable arguments, while public officials decide how much scrutiny those arguments receive. When the choice is war, other people supply the taxes, bear the losses, and live with the destruction. Calling that arrangement national security does not place it beyond moral judgment.
November must remove the protection, not just the officeholders
This is why the 2026 midterms matter. On September 28, Reuters reported that Democrats were preparing investigations into Trump-family ventures and related dealings if they gained control of either chamber, which would give them subpoena power and additional investigative resources. [72] A majority determines more than whose face appears behind the committee microphone. It helps determine whether powerful people must produce records or can continue brushing questions aside.
Promises to investigate are not investigations. Democrats must be judged by what they compel, establish, disclose, and change, not by how magnificently they announce that accountability is coming. Their own history gives us every reason to demand specifics before applauding.
Demand enforceable separation between public office and private financial benefit. Demand timely disclosures that can actually be audited, independent oversight that survives presidential displeasure, and judicial ethics with consequences. Demand that Congress confront war-making rather than outsource responsibility to the president and then congratulate itself for looking concerned.
Winning a chamber will not eject Trump from office, erase his executive authority, or automatically overcome his veto. Even the Iran war-powers resolution would have faced the prospect of a presidential veto requiring a two-thirds override in both chambers. [73] But a Congress willing to investigate and resist is materially different from one organized to protect him.

That is the midterm choice I want Americans to understand. Throw out the protectors, then refuse to become the new majority’s grateful audience. If Democrats want to inherit the gavels without confronting the money, they will have mistaken our disgust for a permission slip. It is not.
Distribute power, not permission
The remedy cannot stop at asking rich people to behave. Piketty’s proposals combine progressive taxation and the circulation of inherited wealth with workers’ decision-making rights, while Wolff emphasizes democratic enterprises. [74] These are different programs, but both confront ownership and control rather than merely cleaning up campaign advertising.
In a 2025 discussion, Piketty argued that a modest billionaire tax is a beginning, not enough by itself to reverse concentration, and proposed using broader wealth taxation to finance capital endowments for everyone. [75] The purpose is not simply to improve a government balance sheet. It is to give people assets and bargaining power of their own.
That is the standard I want applied: does a reform reduce dependence? Can a worker refuse abuse, a tenant challenge exploitation, a candidate survive without a wealthy patron? Taxation, collective bargaining, public services, competitive markets, and democratic ownership should be judged by whether they make those answers less dependent on somebody else’s permission.
The same moral objection applies abroad. Why should other societies accept American entitlement to dictate their development or their trading partners? Calling coercion “economic statecraft” does not transform subordination into freedom. Other people’s independence is not an American policy failure.

Coercion can also send the bill home. Mary Amiti, Stephen Redding, and David Weinstein found that Trump’s 2018 tariffs fell on domestic consumers and importers, reducing aggregate American real income by $1.4 billion monthly by the end of that year. [76] The cost of entitlement becomes collective.

November is an opportunity, not an absolution. Replacing Republican incumbents matters, but it will not by itself dismantle the power that survives changes of administration. The task is not to install kinder managers of an ownership society built for its owners.
I want Americans to stand up for themselves. I want the rest of humanity to enjoy the same right. Neither should have to accept government conducted for the benefit of people who already own far too much.
References
- Federal Reserve ↩
- Federal Reserve ↩
- Federal Reserve methodology ↩
- Federal Reserve ↩
- Piketty, 2021 ↩
- Piketty, 2015 ↩
- Piketty, 2015 ↩
- Saez and Zucman ↩
- American Economic Journal: Economic Policy ↩
- Hudson, 2021 ↩
- Hudson ↩
- Hudson ↩
- Wolff, published excerpt ↩
- Democracy at Work ↩
- National Bureau of Economic Research ↩
- Feigenbaum and colleagues ↩
- Perspectives on Politics, 2009 ↩
- American Economic Review ↩
- Perspectives on Politics, 2014 ↩
- V-Dem ↩
- Kalla and Broockman ↩
- Sachs, 2024 ↩
- Sachs ↩
- Congressional Budget Office ↩
- House Clerk ↩
- U.S. Senate ↩
- Sachs ↩
- Quarterly Journal of Economics, 2022 ↩
- Associated Press ↩
- ProPublica’s investigation ↩
- ProPublica ↩
- Treasury correspondence, pages 1 through 3 ↩
- ProPublica, Milwaukee Journal Sentinel ↩
- Congressional Research Service, Senate roll call ↩
- CNBC ↩
- CNBC ↩
- CNBC, Senate roll call ↩
- CNBC ↩
- CNN ↩
- OpenSecrets, Senate roll call ↩
- CNN ↩
- Hogan Lovells announcement ↩
- Campaign Legal Center’s filed complaint ↩
- Justice Department ↩
- Justice Department ↩
- Politico ↩
- Justice Department sentencing record ↩
- Justice Department ↩
- KPBS ↩
- Thomas disclosure, pages 2, 7, and 8 ↩
- ProPublica ↩
- ProPublica ↩
- Thomas disclosure, page 8 ↩
- ProPublica, Thomas disclosure ↩
- Judicial Conference letter ↩
- Reuters, June 30, 2026 ↩
- Reuters ↩
- Reuters, June 9, 2026 ↩
- Reuters ↩
- Brennan Center analysis ↩
- White House archival biography ↩
- Clinton Presidential Library finding aid, ABC News ↩
- Senate roll call ↩
- Reuters ↩
- Quincy Institute study ↩
- Atlantic Council donor disclosure ↩
- NPR, Politico ↩
- Politico ↩
- Politico’s FEC reporting ↩
- Reuters, Senate roll call ↩
- Reuters ↩
- Reuters ↩
- Reuters ↩
- Piketty, Wolff ↩
- World Inequality Lab ↩
- Journal of Economic Perspectives ↩
Evidence and methods behind the graphics
The graphics state the argument concisely. These notes retain the source records, dates, definitions, and limits needed to examine it. Financial contributions, personal income, disclosed benefits, and criminal findings are kept distinct.
Figure 1. They own the assets. You get the speech.
The top 1% hold 50.9% of corporate equities and mutual-fund shares, while the bottom half hold 0.6%, in the Federal Reserve’s Q2 2026 estimates (Federal Reserve). The comparison exposes the distance between numerical size and ownership, not a measured ratio of political power.
| Wealth-ranked household group | Household share | Equities + fund shares | Total net worth |
|---|---|---|---|
| Top 1% | 1% | 50.9% | 32.5% |
| Next 9% | 9% | 37.2% | 36.4% |
| Next 40% | 40% | 11.4% | 28.8% |
| Bottom 50% | 50% | 0.6% | 2.3% |
Households are not individual voters. Pension entitlements are separately identified. This is not a census of every global stock market. Rounded asset shares total 100.1%.
Evidence: Federal Reserve ownership table.
Figure 2. The country got richer. The bottom half barely did.
From 1980 through 2018, estimated annual pretax income growth averaged 1.4% across adults and 0.2% for the bottom half (Saez and Zucman, Journal of Economic Perspectives). The national average cannot tell readers who collected the gains.
| Income group | Average annual real growth | Period |
|---|---|---|
| All adults | 1.4% | 1980 through 2018 |
| Bottom 50% | 0.2% | 1980 through 2018 |
Equal-split adults aged 20 or older. These are the authors’ estimates, subject to distributional-accounting choices. Income-ranked groups differ from wealth-ranked households in the ownership graphic.
Evidence: Saez and Zucman (2020).
Figure 3. Who owns? Who extracts? Who governs? Who decides?
The article draws on Piketty’s institutional economics, Hudson’s rentier analysis, Wolff’s workplace-democracy argument, and Sachs’s critique of political dependence (Piketty; Hudson; Wolff; Sachs). They are not treated as interchangeable authorities or as unanimous on remedies.
| Scholar | Mechanism | Type of work used |
|---|---|---|
| Thomas Piketty | Accumulation, inheritance, decision rights | Journal research and policy discussion |
| Michael Hudson | Debt, rent, privatized control | Journal political economy |
| Richard Wolff | Workplace authority and surplus | Book excerpt and explanatory transcript |
| Jeffrey Sachs | Donor and lobby dependence | Authored political-economic essays |
Theory, commentary, descriptive data, randomized evidence, and policy projections answer different questions. The research notes document disagreements, including income-measurement and markup debates.
Evidence: Piketty (2021); Hudson (2021); Wolff (2024); Sachs (2024).
The graphic summarizes 4 distinct perspectives, not a jointly authored theory. Piketty examines accumulation, inheritance, taxation, and institutions; Hudson distinguishes production from economic rent; Sachs criticizes donor and lobby influence over government; Wolff advocates democratic control of enterprises. These arguments are not interchangeable, and the graphic does not claim that each author endorses every conclusion in this article. Economic rent concerns scarcity, monopoly, or privileged control beyond the costs of the underlying service; not every rent payment, dividend, or interest charge qualifies.
Figure 4. The safeguards are weakening.
V-Dem reports U.S. Liberal Democracy Index scores of 0.75 in 2024 and 0.57 in 2025, a 24% decline in the reported scores (Democracy Report 2026). That is evidence of deterioration, not an estimate of how much wealthy donors caused it.
| Observation year | Liberal Democracy Index | World rank |
|---|---|---|
| 2024 | 0.75 | 20th |
| 2025 | 0.57 | 51st |
Index range: 0 to 1; higher means more liberal democracy. Values are rounded and have measurement uncertainty. The report examines checks on executive authority, rights, and expression. Election-specific measures were not reassessed in 2025.
Evidence: V-Dem Democracy Report 2026.
Figure 5. The same request. A different door opens.
Revealing donor status increased senior-staffer access from 5.5% to 18.8% in a randomized experiment involving 191 congressional offices (Kalla and Broockman). This measures a specific advantage in access, not purchased votes or a universal corruption rate.
| Meeting request identifies participants as | Senior-staffer access | Design |
|---|---|---|
| Local constituents | 5.5% | Randomized wording |
| Local campaign donors | 18.8% | Randomized wording |
Conducted in 2013; published in 2016. The 3.4× ratio is 18.8 / 5.5. Offices were from 1 party in a particular advocacy setting. Donor-status disclosure was randomized, not actual donations.
Evidence: Kalla and Broockman.
Figure 6. Wealth protects power. Power protects wealth.
Piketty examines the political construction of ownership; Hudson analyzes financial extraction; Farrell and Newman show how control of global network nodes can enable coercion (Piketty; Hudson; Farrell and Newman). The map joins those mechanisms without pretending that every arrow has a measured causal coefficient.
| Connection | Evidence status | Consequence to examine |
|---|---|---|
| Ownership to influence | Theory plus direct access evidence | Unequal ability to reach decision-makers |
| Policy to household resources | Policy-specific distribution estimates | Costs and benefits differ by income |
| Contested primacy to coercion | Conditional political choice | Not inevitable; cooperation remains possible |
| Coercion to domestic costs | Instrument-specific empirical evidence | Tariffs can burden domestic buyers |
This is not a money-flow diagram. Arrow widths do not encode dollars. The dashed international path is conditional, and a reserve-share decline alone does not prove loss of unipolar hegemony.
Evidence: Piketty (2021); Hudson (2021); Farrell and Newman (2019).
The loop summarizes an institutional mechanism, not a measured flow of dollars or a finding that every link operates in every case. Ownership, financing, legislation, and private returns are distinct events. Named cases elsewhere in the article document specific connections; they do not establish a universal quid pro quo.
Figure 7. Taking below. Giving above.
CBO estimated average annual resource losses of $1,200 for the lowest-income tenth and gains of $13,600 for the highest-income tenth under the 2025 reconciliation law (Congressional Budget Office). The distribution shows who gains and loses; it does not establish a particular payment bought a vote.
| Income group | Annual resource change | Main driver |
|---|---|---|
| Lowest-income 10% | −$1,200 | Reduced benefits |
| Highest-income 10% | +$13,600 | Lower federal taxes |
Average during 2026 through 2034, constant 2025 dollars, against the January 2025 baseline. Resources include in-kind benefits. Not observed losses in every household and not a complete incidence estimate of all taxes.
Evidence: CBO distributional analysis.
Figure 8. A few votes can protect a fortune.
The House passed H.R. 1 by 218 to 214 in July 2025; 2 yes-to-no switches would have produced a losing tie (House Clerk). The Senate divided 50 to 50 before the vice president broke the tie; 1 additional no would have defeated passage (U.S. Senate).
| Chamber | Observed senator/member vote | Switches needed to defeat | Counterfactual |
|---|---|---|---|
| House | 218 yes / 214 no | 2 yes-to-no switches | 216 yes / 216 no: fails |
| Senate | 50 yes / 50 no | 1 yes-to-no switch | 49 yes / 51 no: fails |
All other votes are held unchanged. This illustrates leverage at the decisive margin, not proof that any vote was bought. All House and Senate Democrats opposed this law. An already nearly assembled coalition is different from buying support from scratch.
Evidence: House Clerk, roll call 190; U.S. Senate, roll call 372.
Figure 9. The holdout wanted better terms for owners.
Wisconsin Republican Sen. Johnson threatened to withhold support before the 2017 pass-through provision was expanded. Uihlein and Hendricks support totaled about $20 million in 2016; their combined 2018 deductions were $215 million (ProPublica). Wisconsin Republican Sen. Johnson later acknowledged that Pacur benefited while defending broad business-tax relief (Milwaukee Journal Sentinel).
| Stage | Amount or action | Recipient or beneficiary |
|---|---|---|
| 2016 support | Approximately $20 million | Groups backing Wisconsin Republican Sen. Johnson |
| 2017 intervention | Threatened no; secured expansion | Pass-through business owners |
| 2018 deductions | $215 million | Uihleins and Hendricks |
| Personal interest | Benefit acknowledged; amount not established | Pacur |
No criminal exchange is established. The deductions include the whole provision, not just the amendment’s incremental benefit. No return-on-donation ratio is calculated.
Evidence: ProPublica; Milwaukee Journal Sentinel.
Figure 10. One indispensable vote. A tax privilege survives.
Then-Arizona Democratic Sen. Sinema secured removal of a carried-interest tightening expected to raise approximately $14 billion over a decade, after receiving at least $2 million in securities-and-investment contributions during the reported multicycle period (CNBC). The Senate divided 50 to 50 before the vice president voted yes (U.S. Senate).
| Measure | Value | Meaning |
|---|---|---|
| Industry contributions | At least $2 million | Start of 2018 cycle through August 2022 reporting |
| Proposed revenue | Approximately $14 billion | Over a decade |
| Senators’ final vote | 50 yes / 50 no | Vice president voted yes |
The bill had many provisions, including major climate and health measures. Removing this proposal did not repeal all taxation of carried interest. No criminal quid pro quo is established.
Evidence: CNBC; U.S. Senate.
Party labels follow the period discussed, rather than retroactively changing the record.
Arizona Sen. Kyrsten Sinema was a Democrat during the August 2022 negotiations and registered
as an independent on December 9, 2022
(CNBC).
West Virginia Sen. Joe Manchin was a Democrat during the 2021 and 2022 events discussed and
registered as an independent on May 31, 2024
(NPR).
The historical labels describe their offices and affiliations then; they do not present either as
a current senator. References to former Arizona independent Sen. Sinema’s post-Senate career
identify the affiliation under which she finished her Senate service.
Figure 11. The senator collected on two different tracks.
CNN documented more than $536,000 in Enersystems income and an ownership bracket of $1 million to $5 million for 2021, alongside more than $400,000 in energy-interest campaign money during that year’s third quarter (CNN). The graphic separates the owner’s income from the politician’s funding.
| Financial category | Reported amount | Period |
|---|---|---|
| Personal business income | >$536,000 | 2021 |
| Ownership value | $1 million to $5 million | 2021 disclosure |
| Energy-interest campaign receipts | >$400,000 | Q3 2021 |
The original then-West Virginia Democratic Sen. Manchin Senate form was not independently downloaded. Values are attributed to CNN’s filing analysis. Neither business income nor campaign donations are labeled bribes.
Evidence: CNN.
Figure 12. Sometimes it is not a conflict. It is a crime.
Former California Republican Rep. Cunningham admitted at least $2.4 million in bribes connected to defense-contracting influence and omitted benefits from House disclosures (Justice Department). Former New Jersey Democratic Sen. Menendez was sentenced to 11 years after a jury conviction involving cash, gold, and other benefits for official assistance (Justice Department).
| Case | Monetary measure | Legal result |
|---|---|---|
| Former California Republican Rep. Cunningham | At least $2.4 million admitted bribes | 100-month sentence in 2006 |
| Former New Jersey Democratic Sen. Menendez | >$480,000 cash and >$100,000 gold found at home | 11-year sentence in January 2025 |
These are different monetary measures, so the image is not a comparative bar chart. Former California Republican Rep. Cunningham was pardoned in 2021 after serving his sentence. Former New Jersey Democratic Sen. Menendez’s appeal remained unresolved in September 24, 2026 reporting.
Evidence: Justice Department; Justice Department.
Figure 13. A robe does not make private benefits disappear.
Thomas’s filing lists Crow-provided travel and acknowledges an omitted property transaction (Thomas financial disclosure). ProPublica documented a $6,200 tuition transfer and the subsequent acknowledgment of support at 2 schools (ProPublica). The Judicial Conference declined to act on a referral request in January 2025 (Judicial Conference letter).
| Category | Record | Limit |
|---|---|---|
| Travel | 2022 disclosure, pages 2 and 7 | Interpretation of earlier disclosure rules disputed |
| Tuition | $6,200 monthly payment documented | Not a lifetime total |
| Property | Filing rounds combined sale to $133,000 | Not a personal gift; Thomas says capital loss |
| Referral | January 2, 2025 letter | Not adjudication of all allegations |
The filing’s rounded $133,000 differs from the deed-based $133,363 reported by ProPublica. The image uses the filing’s number and does not portray sale consideration as a gift.
Evidence: Thomas financial disclosure; ProPublica; Judicial Conference letter.
The redesigned graphic uses the deed-based $133,363 total reported by ProPublica, rather than the rounded $133,000 in Thomas’s filing. The sale involved multiple owners. Neither amount is labeled a cash gift to Thomas.
Figure 14. The family collects. The watchdogs go.
Reuters reported more than $1.4 billion in 2025 income from family crypto ventures, with Trump remaining a trust beneficiary while his children managed the businesses (Reuters). The early second-term purge removed more than a dozen inspectors general (Brennan Center).
| Dimension | Finding | What not to infer |
|---|---|---|
| Crypto-venture income | >$1.4 billion in 2025 | Not a proved bribery total |
| Management | Children manage; Trump remains beneficiary | Not divestment |
| Watchdogs | >12 inspectors general fired overnight early in term | Not a quantified cause of business income |
No numerical ranking against all Democratic presidencies is claimed. The White House denies conflicts. The article attributes ‘unprecedented’ to the specific conflict assessed by ethics experts.
Evidence: Reuters; Brennan Center.
Figure 15. Who gets the microphone when war is debated?
In Quincy’s selected Ukraine coverage, 1,064 of 1,247 think-tank mentions involved institutions with defense-sector support (Quincy Institute). The Atlantic Council separately disclosed 2021 donations of $100,000 to $249,999 each from Lockheed Martin and Raytheon Technologies (Atlantic Council).
| Funding classification | Mentions | Share |
|---|---|---|
| Defense-sector support | 1,064 | 85.3% |
| No identified defense-sector support | 147 | 11.8% |
| Unknown | 36 | 2.9% |
Selected New York Times, Washington Post, and Wall Street Journal coverage, not all news. Quincy advocates restraint. Its study does not establish donor direction, accuracy of individual articles, or causes of Russia’s invasion.
Evidence: Quincy Institute; Atlantic Council.
Figure 16. Change the majority. Then demand the records.
The March 4, 2026, Iran motion failed 47 to 53, with Pennsylvania Democratic Sen. Fetterman voting no and Kentucky Republican Sen. Paul voting yes (U.S. Senate). Democrats have announced plans to investigate Trump-family dealings if they win control of a chamber (Reuters).
| Side | Party composition | Total |
|---|---|---|
| Advance motion | 44 D + 2 I + 1 R | 47 |
| Block motion | 52 R + 1 D | 53 |
| Counterfactual | 4 no-to-yes switches | 51 to advance / 49 against |
The calculation holds all other votes fixed. A successful discharge motion does not itself end hostilities. Subpoenas may be contested, and oversight plans are not completed findings.
Evidence: U.S. Senate; Reuters.
Figure 17. Dollar dominance erodes. Leverage remains.
The dollar’s reserve share declined from 71.5% in 2001 to 57.8% in 2024, while it remained central to cross-border debt and banking (Federal Reserve, July 2025 data tables). This is evidence of diversification alongside continuing leverage, not proof that all American hegemony has ended.
| Selected year | Dollar share of disclosed official reserves |
|---|---|
| 2001 | 71.5% |
| 2010 | 62.3% |
| 2020 | 58.9% |
| 2024 | 57.8% |
A single historical data vintage is retained. The graph is not a current reserve estimate. Dollar-denominated shares in 2024: foreign-currency debt issuance 60.6%; international and foreign-currency banking claims 56.4%. Currency power is only 1 dimension of international power.
Evidence: Federal Reserve historical data.
Figure 18. Washington applies pressure. Americans get a bill.
Research on the 2018 tariffs found domestic importers and consumers bore the tariff burden, with estimated aggregate U.S. real-income losses of $1.4 billion per month by year-end (Amiti, Redding, and Weinstein). A policy advertised as pressure on foreigners can reduce economic welfare at home.
| Measure | Finding | What it is not |
|---|---|---|
| Tariff incidence | Domestic importers and consumers | Proof that every future tariff has identical incidence |
| Aggregate real-income loss | $1.4 billion per month by end-2018 | Customs revenue or a per-household tax bill |
Historical 2018 finding, published in 2019. The estimate cannot be relabeled as a 2026 burden or allocated wholly to wage earners without additional evidence.
Evidence: Amiti, Redding, and Weinstein (2019).
Scott Ortkiese | Throughline Synthesis | so@throughlinesynthesis.com